

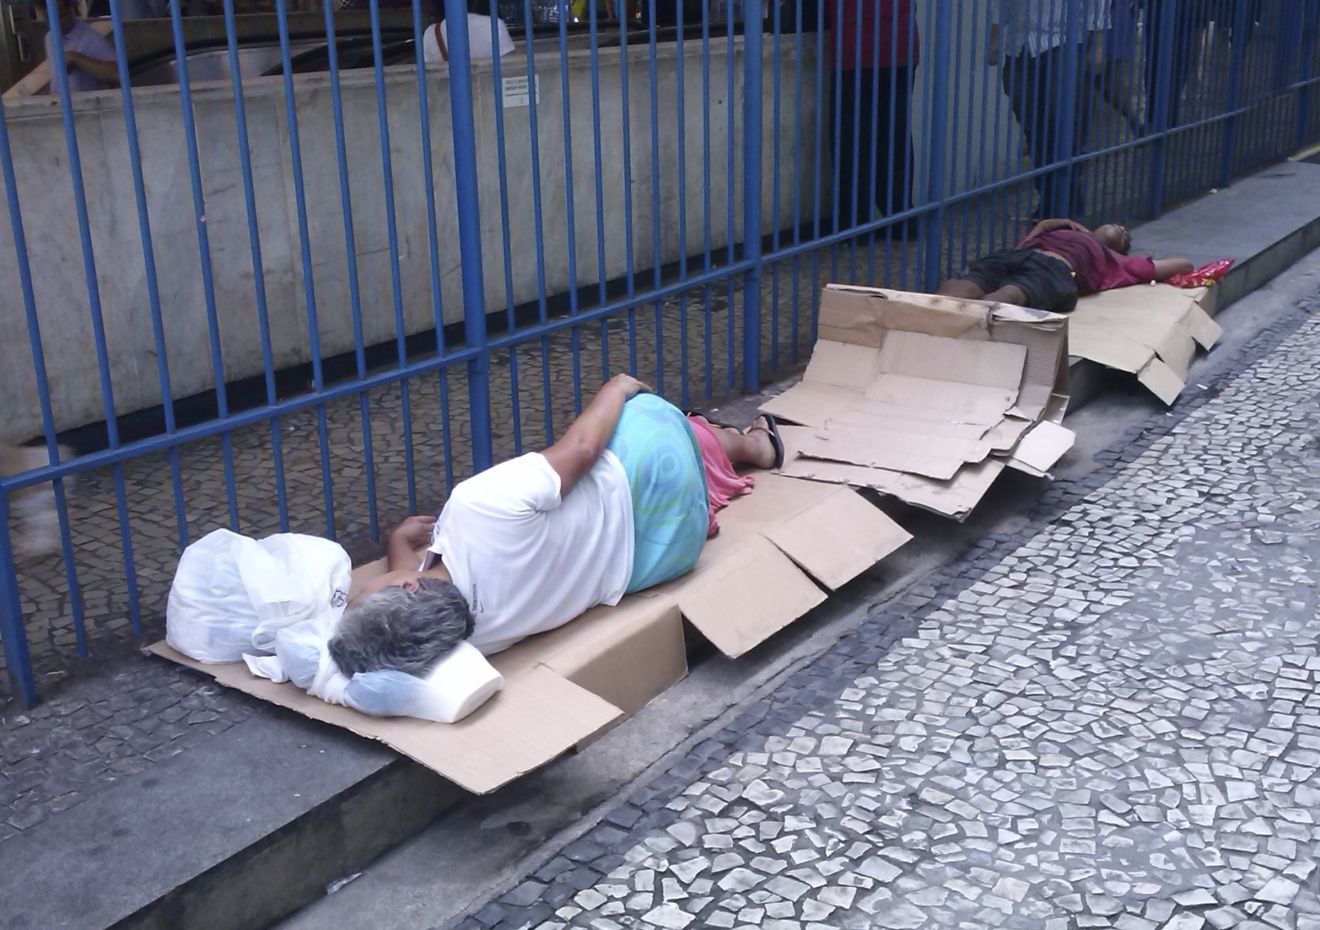
The mobile phone could solve the problem of the global unbanked, but it will not solve global poverty
According to the Global Findex created by the World Bank, three quarter of the world’s poor do not have a bank account. There are 2.5 billion of such people for whom a lack of money is an obvious reason for the situation, but travel distance, costs, and paperwork are also contributing factors.
However, a billion of them have a mobile phone, which has become their link to financial services.
“The adoption of mobile phones has enabled some of the poorest economies on earth to leapfrog ahead of developed nations when it comes to tech-driven financial solutions,” states Albert Chu, Visiting Research Fellow at the Singapore Management University Sim Kee Boon Institute (SKBI) for Financial Economics. “Adults in sub-Saharan Africa are three times more likely to use mobile money as their counterparts in Europe and North America.
“It’s very clear that FinTech for financial inclusion and impact investing can literally be a life-changing platform.”
Mobile phones + FinTech = Changing lives for the better
FinTech, a contraction of Financial Technology, is about using software to provide financial services. It was the topic of discussion in a panel titled "Opportunities of Impact Investing in FinTech for Financial Inclusion" at the recent SKBI Conference 2015, where the impact of, and opportunities provided by, the very high adoption rate of mobile phones in developing countries were hot topics of discussion.
A panelist, founder of social enterprise Unreasonable Group, Daniel Epstein, relates how someone he used to work with started a company called Off Grid Electric in sub-Saharan Africa. Xavier Helgesen’s idea to replace kerosene with solar energy as a source of light not only led to a more reliable and healthier option, it was also made possible by the prevalence of mobile banking as illustrated by the Global Findex: 16 percent of sub-Saharan Africans have “used a mobile phone to pay bills, send or receive money in the past 12 months” compared to just three percent for the rest of the developing world.
“1.3 billion people in the world don’t have access to electricity and therefore have to use dirty fuel, most commonly kerosene,” Epstein explains. “The thing about kerosense is that it is dangerous and produces toxic fumes, and is a poor source of light.
“If you are spending US$3 a week on kerosene – and people are making US$4 a day – Off Grid Electric will come to your front door and say, ‘Would you like to go from kerosene to solar, and we won’t charge you anything up front. Instead, we’ll charge you US$2.90 a week.’ They say yes, and every week you’ll pay US$2.90 with your mobile phone to Off Grid electric. If you don’t, they turn off your lights. What they have effectively create is a solar electrified grid in some of the poorest regions in Africa.”
Using Off Grid Electric's operations in Tanzania (70 percent mobile phone penetration rate with annual subscriber growth of over 20 percent) as a case study, Epstein illustrated how startups can ride on FinTech to solve an important problem and make money at the same time. He also pointed to developing countries such as Vietnam, Botswana, and Brazil which all have over 100 mobile phone subscriptions per 100 people (all over 120), and how this presents massive opportunities for profitable innovation.
Banks: Frogs in slowly boiling water
With 2.5 billion people worldwide without a bank account, the opportunity for banks to get a slice of the business by developing FinTech solutions is clear for all to see. According to another panel member, managing director of Startupbootcamp FinTech, Nektarios Liolios, the financial establishment could care less about the unbanked.
“The new distributed way of doing things allows people to do what startups do, which is to find solutions to problems: there is a need, and there is technology that is accessible, people will build startups. The question is: what do the banks and traditional infrastructure do to participate in all that?
“They do nothing. When I talk to banks about impact initiatives, they come from a CSR angle. To them, sometimes it’s a matter of box-ticking; there’s very little genuine interest to be part of the solution to a real problem. Fundamentally, they don’t care that much about these people.”
Danny Quah, executive vice president of Fullerton Financial Holdings, explains why banks are not getting into the action as yet.
“At this point in time, the banks are still making good money. If you are still making good money, or relatively good money,” he quipped to laughs from the audience, “then the urgency of looking at a breakaway technology to transform the whole company takes a back seat.
“If you look at China, the loan spread is practically controlled, the banks takes 400 to 500 basis points. With that kind of spread, looking at breakaway technology is not on the radar screen. There will come a point where banks become frogs in a pot of boiling water, and the banks will ask themselves, ‘At what stage do I jump out of this water?’ It’s still early days for the banks.”
Can mobile banking eradicate poverty?
Whether or not banks join the fray, it is clear that FinTech and mobile phones have the potential to lift the world out of poverty. Bill Gates, in his 2015 annual letter, said thus:
“Already, in the developing countries with the right regulatory framework, people are storing money digitally on their phones and using their phones to make purchases, as if they were debit cards. By 2030, 2 billion people who don't have a bank account today will be storing money and making payment with their phones. And by then, mobile money providers will be offering the full range of financial services, from interest-bearing savings accounts to credit to insurance.”
In effect, mobile phones will become de facto banks for the global unbanked, which would then render the term obsolete. But will it lead to the eradication of poverty, as is the goal of Gates?
“Poverty as defined by living on less than US$2 a day, yes I think we can eradicate it,” Epstein says before adding, “but I think poverty in reality is relative, and we cannot eradicate income disparity. However, I believe that for the first time in human history we have the tools and consciousness to shift a lot of these massive problems we now face.
“Ending poverty in 15 years, however, is unlikely in my view.”
Follow us on Twitter (@sgsmuperspectiv) or like us on Facebook (https://www.facebook.com/PerspectivesAtSMU)